AMD Q3 2026 Earnings: Data Center Was More Than All the Growth
AMD's Q3 2026 earnings: Data Center added $4.2B of a $4.1B revenue gain while everything else shrank. Inventory rose 35% and debt 119% in one quarter.
In AMD's Q3 2026 earnings, total revenue grew by $4.13 billion. Its Data Center segment grew by $4.21 billion. Run that subtraction and the rest of the company, meaning PCs, gaming and embedded chips, got slightly smaller. That's the part the "+97%" headline leaves out.
AMD reported the results on Nov. 3, 2026. According to its press release, revenue was a record $13.377 billion, up 45% from $9.246 billion a year earlier, and Data Center revenue was "a record $8.5 billion, up 97% year-over-year." The company's post on X, sent at 21:17 UTC that day, just points to that release.
AMD's post on X, Nov. 3, 2026, linking to the third-quarter results release (@AMD)
The post says: "$AMD reports Third Quarter 2026 financial results. View non-GAAP financial measures reconciliation & cautionary statement." There's no extra thread from AMD with technical detail, so the numbers live in the release and in AMD's 8-K slides, which we read in full.
Subtract the data center
The slides give segment revenue to the million. Data Center went from $4,341 million to $8,546 million. Client and Gaming went from $4,048 million to $3,722 million, and Embedded from $857 million to $1,109 million. Add those last two and "everything else" went from $4,905 million to $4,831 million, a 1.5% drop. These sums are ours, from AMD's table.
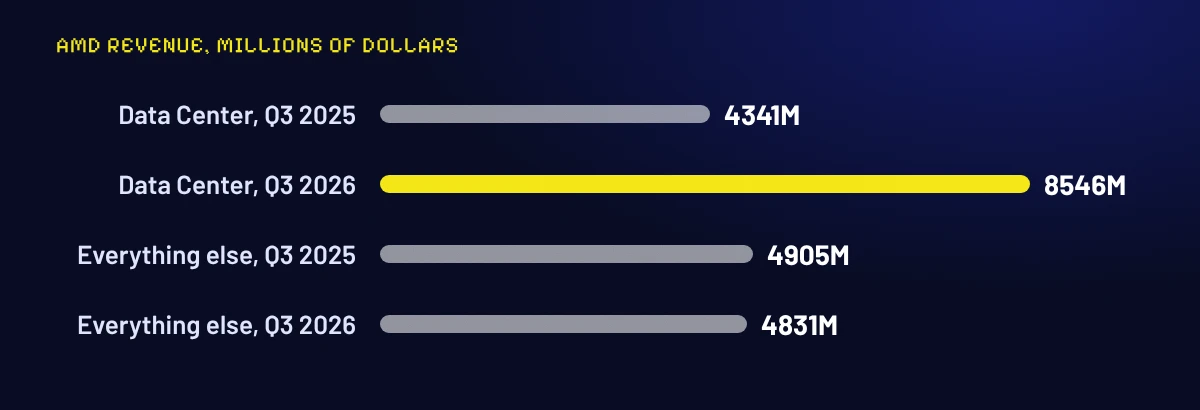
Data Center is now about 64% of revenue, up from about 47% in the same quarter last year. Gaming alone fell 40% to $773 million, which AMD blames on "lower semi-custom and graphics revenue." Client rose 7% to $2.9 billion on Ryzen mobile chips. Embedded's 29% gain only just covered the hole.
What AMD doesn't give you is the split inside Data Center. It credits "strong demand for AMD EPYC processors and the launch of AMD Instinct MI450 Series GPUs," but never says how many dollars came from each. If you want to know how big the AI GPU business is on its own, this release can't tell you.
Where the cash went first
Growth like this is paid for before it's collected. The balance-sheet slide compares the end of Q3 with the end of Q2:
- Inventories rose from $8,468 million to $11,463 million, up 35%.
- Accounts receivable rose from $7,281 million to $9,209 million, up 26%.
- Total debt rose from $3,226 million to $7,079 million, up 119%, including a $4.75 billion senior-notes offering in August.
- Cash and short-term investments rose from $13,111 million to $15,776 million.
Our reading: this isn't a warning sign by itself. A company building racks for customers has to buy parts first. But it does mean the fourth quarter has to show up. AMD guides to about $17 billion, plus or minus 3%, which is $16.5 to $17.5 billion. The midpoint is $3.6 billion above Q3, our subtraction, and AMD says it's up about 27% sequentially. Non-GAAP gross margin is guided to about 55%, a point below Q3's 56%, with operating expenses of about $3.75 billion against $3.56 billion.
The $1.1 billion that isn't operations
GAAP net income was $2,428 million. Non-GAAP net income was $3,471 million. Most of the gap is not a surprise: stock compensation and amortization of acquired intangibles. The odd line is "change in fair value of warrant liability," which adds back $1,097 million, or $0.66 per share.
AMD's footnote says this is the quarterly remeasurement of "warrants issued to certain customers" and that it "is driven by changes in AMD's stock price and other valuation assumptions." The release doesn't name the customers or the conditions. The slides do list the stock price's effect on "the fair value of customer warrants" among AMD's risk factors.
The whole gap between GAAP and non-GAAP earnings per share is $0.63 ($2.09 versus $1.46), so this one item is larger than the difference, with taxes and other adjustments pulling the other way. The practical point: because the charge follows AMD's share price, GAAP profit can swing in a quarter where the business itself holds steady. Read the reconciliation before comparing two quarters.
Five names and a verb
The release says Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure "are running models and workloads on the first AMD Helios rackscale solutions." That's the strongest customer line in the document, and it's also one verb: running. No volumes, no racks, no revenue by customer, and no word on whether this is production or testing. Separately, AMD says HPE "announced that Vultr will deploy" the first Helios by HPE systems, which is a future plan, not a shipment.
ROCm 10 is old news inside a new release
The release lists "AMD ROCm 10 was released" as a recent highlight, which reads like a November event. AMD's own blog is dated Aug. 27, 2026. It also carries the only performance numbers around: 3.3x higher average inference throughput across three models and 2.4x higher training throughput, both on eight MI355X GPUs, using a preview of ROCm.AI built on ROCm 7.2.2 against ROCm 7.0. AMD adds that the results "should not be presented as universal ROCm 10 performance uplifts," and they aren't from MI450 or Helios hardware.
One quarter of arithmetic to run yourself
Take the Q4 midpoint of $17.0 billion and suppose everything outside Data Center simply held at Q3's $4.83 billion. That's our assumption, since AMD's release doesn't guide by segment. Data Center would then have to reach about $12.2 billion, roughly 42% above Q3's $8.55 billion. If you want to know whether AMD is on track, don't watch the headline growth rate. Watch whether Data Center's share of revenue keeps climbing and whether the inventory line stops growing faster than sales.
Source: AMD Investor Relations, AMD Reports Third Quarter 2026 Financial Results
Latest
- 01Linux TCP Flaw CVE-2026-98432: Ubuntu's Fix Is Still Opt-InWorld · 2026-11-04
- 02Microsoft: Fake Installers Rent Out Your PC in Three WaysWorld · 2026-11-04
- 03Fireworks Ultrafast: 1,500 What? Europe Capacity Waits for 2027Products · 2026-11-04
- 04Vercel Security Review: What a Per-Push Scan Covers and CostsProducts · 2026-11-04
- 05FlashProve: What Anthropic's Provable Inference Speed MeasuresWorld · 2026-11-03